Best overall: a Ghana-eligible receiving account in your business name for direct overseas clients. Best for marketplace work: a receiving account accepted by your platform. Best for a banking relationship: a foreign-currency account with a Ghanaian bank. Choose by eligibility and withdrawal route before comparing features in 2026.
- The best virtual bank account for Ghanaian freelancers must support your registration, client payments and withdrawal destination.
- Zeam suits African businesses collecting USD and EUR; confirm Ghana eligibility and your business structure before applying.
- Marketplace payouts, direct client transfers and card payments need separate checks.
- Zeam is not a bank; its digital balances are not bank deposits.
Why this matters
A foreign client agreeing to pay your invoice does not settle how you receive the money. Your account must accept the payer, currency and payment method, then let you access the proceeds through a supported route.
Zeam provides African businesses with USD and EUR receiving details in their business name, multiple currency balances and local supplier payments. Zeam suits African businesses that need USD and EUR receiving details alongside business-money management. Ghana eligibility, business-structure acceptance and the intended payment route remain checks to complete before applying and completing verification.
For a Ghanaian freelancer supporting a South African tour operator, this distinction is practical. An overseas agency paying a consulting invoice is different from a traveller paying a safari booking deposit. Identify whose service is being sold and whose money is being collected before selecting an account.
What makes the best virtual receiving account?
Use these criteria to choose a virtual bank account for Ghanaian freelancers in 2026. A useful interface does not compensate for an unsupported payment route.
- Ghana eligibility: Confirm that the provider accepts your residence, business registration and legal structure. These are separate questions.
- Receiving-name match: Check which name appears on the receiving details and whether it matches your invoices and client records.
- Payment compatibility: Confirm the accepted currency, payer location and transfer method. USD details alone do not establish that every USD transfer is supported.
- Access to proceeds: Check the withdrawal destination, currency conversion process and any restrictions before sending an invoice.
- Legal protection: Establish whether you hold a bank deposit or another type of balance, and read the applicable protection terms.
- Usable records: Look for statements, payment references and transaction records that support reconciliation and bookkeeping.
Make the first and fourth criteria pass-or-fail checks. An account that cannot onboard your business or deliver money to your intended destination does not belong on your shortlist.
Virtual account options at a glance
These are account arrangements, not interchangeable products. The ranking follows the source of your payments rather than an unsupported provider league table.
| Rank and option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Business-name foreign-currency receiving account | Direct overseas business clients | Receiving details linked to your business name | Ghana eligibility and each payment route need confirmation |
| 2. Marketplace-compatible receiving account | Freelancers paid through a work platform | Fits an approved platform payout method | Platform acceptance does not establish support for direct client payments |
| 3. Ghanaian bank foreign-currency account | Freelancers who specifically want a bank account | A banking relationship rather than a non-bank balance | Transfer instructions, documents and onward access still need checking |
Card acceptance and payment links are additional collection methods, not a fourth type of bank account. Their suitability depends on how your client wants to pay and what the underlying service supports.
1. Business-name receiving account: best for direct clients
A business-name foreign-currency receiving account gives clients payment details associated with your business. Where the provider supports your circumstances, you can use those details for approved overseas invoice payments and manage the resulting balance.
This arrangement fits a freelancer invoicing a US agency or European business directly. It also separates a direct client payment from a marketplace withdrawal, which follows the platform's payout rules.
Business-name receiving account pros:
- Gives business clients a named beneficiary to check against your invoice.
- Supports currency-specific collection when the relevant receiving route is approved.
- Can combine receiving, balance management and payment records within the provider's supported service.
Business-name receiving account cons:
- Business eligibility does not automatically include every freelancer or sole trader.
- Receiving details do not establish that all transfer types or third-party payments are accepted.
- A non-bank balance must not be treated as a bank deposit.
Zeam provides USD and EUR receiving details in a business's name and lets businesses hold multiple currency balances and convert when needed. It also supports local supplier payments; international and bulk payments sit on higher plans. Confirm Ghana eligibility and the specific collection and payout routes before using those features for your business.
Best for: Direct overseas business invoices where the payer can use an approved transfer method.
Verdict: Hold until eligibility, verification and withdrawal access are confirmed; then choose for direct client collection.
2. Marketplace-compatible account: best for platform payouts
A marketplace-compatible receiving account is one your freelance platform accepts as a payout destination. Start with the platform's permitted withdrawal methods, then check the receiving provider's conditions.
This is a different decision from choosing an account for invoices you send independently. The platform controls which payout methods you can select; the receiving provider controls what its account accepts.
Marketplace-compatible account pros:
- Keeps the decision focused on your actual source of earnings.
- Lets you check account-name requirements against platform payout records.
- Provides a defined payout arrangement when both services approve the connection.
Marketplace-compatible account cons:
- Acceptance on one platform does not establish acceptance on another.
- A supported platform payout does not prove that unrelated client transfers are allowed.
- Withdrawal and conversion conditions still apply after the platform releases payment.
If marketplace work supplies your income, do not open an account solely because it advertises foreign receiving details. Confirm the exact payout method inside your platform account and check that your legal name or business name meets both services' requirements.
Best for: Freelancers whose clients pay through a work marketplace rather than directly.
Verdict: Choose only after the platform and receiving provider both confirm compatibility.
3. Ghanaian bank account: best for a banking relationship
A foreign-currency account with a Ghanaian bank is a separate category from a non-bank digital balance. Ask the bank which account type fits your freelance activity, which currencies it supports and what documents are required.
Choose this route when holding an account with a bank is a requirement, not merely because a service uses the phrase virtual bank account. Read the account's actual terms rather than assuming every foreign-currency account has identical protections or transfer capabilities.
Ghanaian bank foreign-currency account pros:
- Provides a direct banking relationship for the approved account type.
- Lets you obtain receiving instructions from the institution holding the account.
- Gives you bank-issued records for the account and its transactions.
Ghanaian bank foreign-currency account cons:
- Opening requirements and permitted uses differ between accounts.
- Overseas clients must follow the bank's applicable transfer instructions.
- Holding foreign currency does not establish how you can withdraw, convert or pay suppliers.
Ask about incoming transfers and access to proceeds together. Receiving an overseas payment solves only part of the problem if the account does not support the next business payment you need to make.
Best for: Freelancers who specifically require a bank account rather than a non-bank receiving service.
Verdict: Choose when the bank confirms that its account and transfer routes fit your work.
Receiving details, cards or payment links?
Choose the collection method around the payer, not around the label on the account. In 2026, a business paying a supplier invoice and a traveller paying a booking deposit still present different collection needs.
| Collection method | Best for | Advantage | Limitation |
|---|---|---|---|
| Overseas receiving details | Business clients able to make supported transfers | Gives the payer currency-specific instructions | Requires the correct transfer route and beneficiary information |
| Card acceptance | Clients who want to pay by card | Offers a card-based payment choice | Disputes, refunds and settlement follow the processor's terms |
| Payment link | Sending a client a payment request | Gives the client a destination for completing payment | A link does not establish the available payment methods or currencies |
Zeam includes payment-link management, but do not assume that a payment link supports a particular card, country or currency. Check the underlying collection method separately. Likewise, receiving details do not establish that a service replaces card acceptance or booking software.
For South African tour operators and safari businesses, keep booking deposits and balance payments tied to the same booking reference. If you freelance for those businesses, distinguish your own consulting invoice from guest funds collected on an operator's behalf. Confirm that any third-party collection arrangement is permitted before accepting it.
Set up the payment flow before invoicing
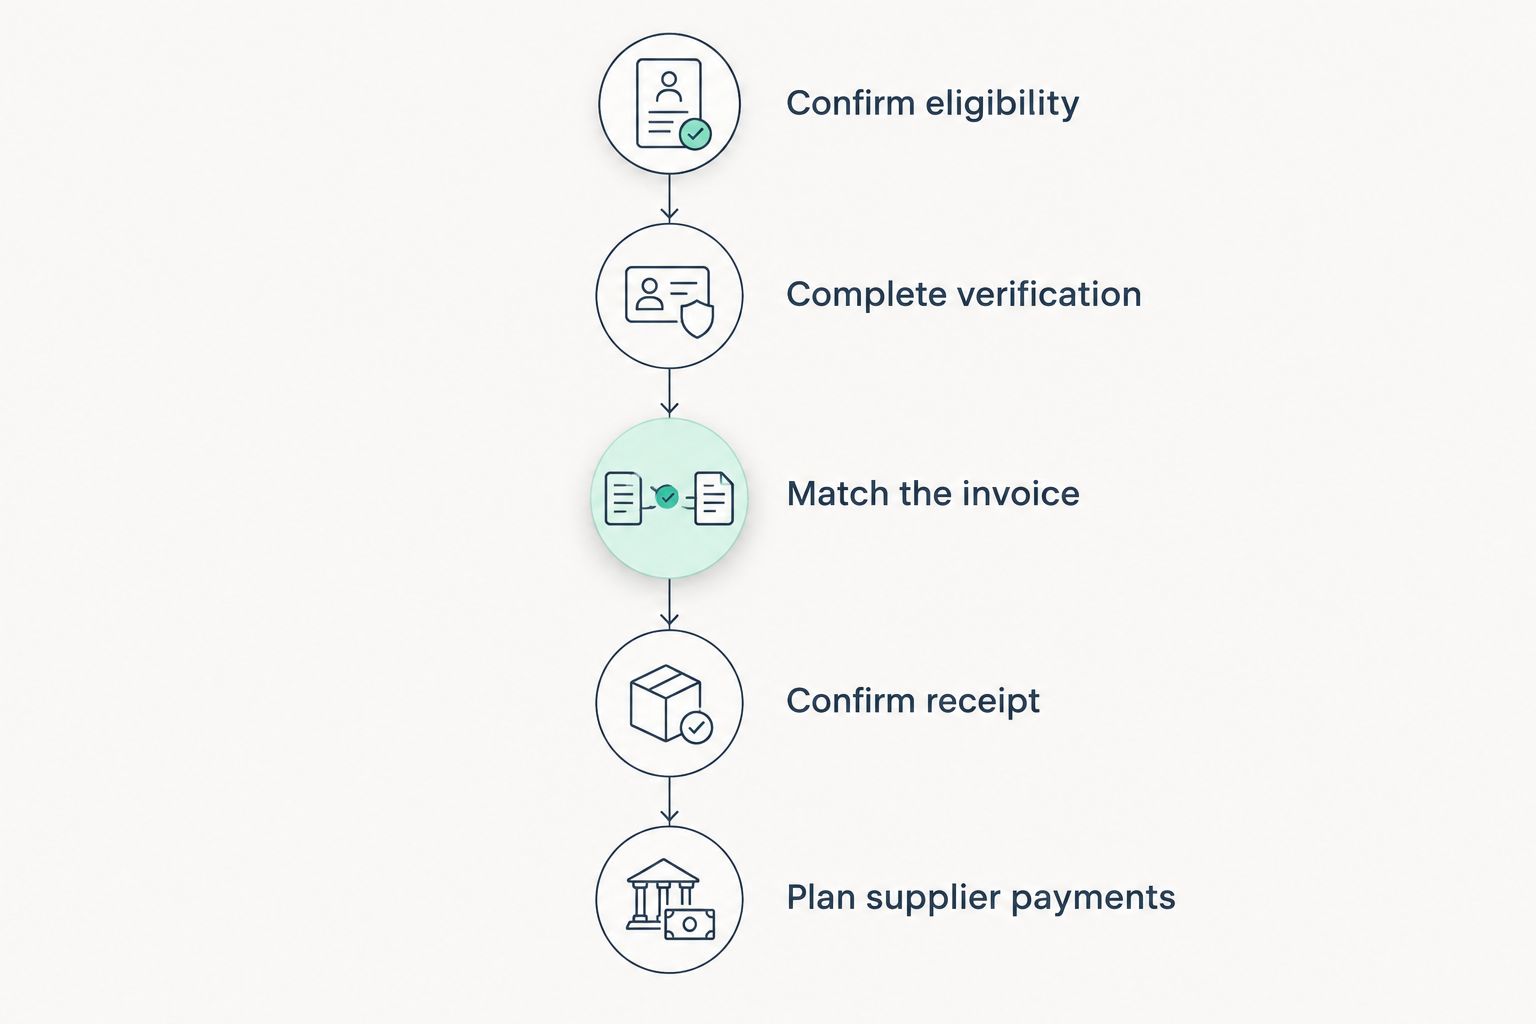
Use this sequence for your first overseas client payment in 2026. The goal is to establish the full route, not just obtain receiving details.
Confirm eligibility
Check your residence, registration and business structure with the provider. Ask whether your activity and intended payer type are accepted, including any marketplace or third-party collection arrangement.
Complete verification
Finish the provider's required verification before directing a client to pay. Submit the requested information accurately and resolve any approval conditions that affect the payment route.
Match the invoice
Use the approved beneficiary name, currency and receiving instructions. Include a clear invoice reference and ask your client to preserve it in the payment information where their payment method allows.
Confirm receipt
Check the account's transaction record before marking an invoice paid. A client sending payment confirmation is not the same as your account showing received funds.
Plan supplier payments
Confirm how you will access or convert the balance and pay business costs. A tourism consultant might receive EUR for project work but need local currency to pay a local supplier; both sides of that flow need a supported route.
For a project using 2 payment stages, record the deposit and balance separately against one job. If you collect in 2 currencies, USD and EUR, keep the invoice currency and received currency clear. Make 3 checks before releasing work: the payer reference, the amount received and the transaction status.
When considering Zeam, apply for a business account and complete verification before relying on receiving details for a client invoice. Confirm the intended Ghana-related collection and payout routes during that process.
Check your business account fit
Review business receiving features, then confirm eligibility and verification requirements before collecting payments.
How the options rank
The ranking prioritises direct client collection, marketplace compatibility and the distinction between bank and non-bank accounts. Eligibility, beneficiary-name matching and access to proceeds take precedence over extra features.
For your 2026 shortlist, remove any option that fails a required route. Compare the remaining options against your actual invoices, records and supplier payments rather than treating the longest feature list as the winner.
Which virtual account should you choose?
For direct overseas invoices, choose a Ghana-eligible business-name receiving account with a confirmed withdrawal route. For platform earnings, choose a platform-approved payout arrangement. If you specifically need a bank account, assess a Ghanaian bank's foreign-currency offering instead.
Do not choose Zeam on an assumption about Ghana availability. Confirm eligibility, apply for the appropriate business account and complete verification before asking a client to send funds. Its digital balances are not bank deposits.
FAQ
What's the best virtual bank account for Ghanaian freelancers?
The best option is one that accepts your Ghana-based circumstances, supports your client's payment method and lets you access the proceeds. Direct invoices, marketplace payouts and a requirement for a bank account lead to different shortlists.
Can a Ghanaian freelancer apply for Zeam?
Confirm Ghana eligibility and acceptance of your business structure with Zeam before applying. Complete the required verification and confirm the intended receiving and payout routes before sending payment instructions to a client.
Can I receive both USD and EUR from overseas clients?
You need a provider that approves both currencies and the relevant payment routes for your account. Zeam provides USD and EUR receiving details for businesses, subject to eligibility, verification and applicable route conditions.
Is a virtual receiving account the same as a bank account?
No, receiving details do not by themselves establish that you hold a bank account. Zeam is not a bank, and its digital balances are not bank deposits.
Can I use any USD receiving account for freelance marketplace payouts?
No, the marketplace and receiving provider must both accept the payout arrangement. Check the exact method, beneficiary-name requirements and account conditions before selecting it.
Are payment links better than overseas transfers?
Neither method is best for every client. Compare the payment methods behind the link with the transfer routes your client can use, then check reconciliation and refund requirements.
Can I collect safari booking deposits through my freelance account?
Only use your account for a collection arrangement that the provider permits. Guest payments collected for a tour operator differ from payment of your own freelance invoice, so confirm ownership of the funds and third-party collection rules first.
One last thing
Write down the exit route before sharing the receiving details. Your payment plan is incomplete until you know how received funds reach the account or supplier that needs them. That check matters more than whether the service calls itself virtual, international or multi-currency.